Your Public Insurance Adjusting Firm Is Losing $9,000+ a Month to Missed Calls
A homeowner in Cape Coral is standing in her kitchen doing math that doesn't work. Her insurer has just paid $9,400 on a roof and water damage claim — and the roofer's real estimate is $31,000. The difference comes out of her savings, or the roof doesn't get fixed. Her neighbor had the same gap, hired a public adjuster, and got the claim reopened and paid properly. That evening, check in hand, she starts calling public adjusters.
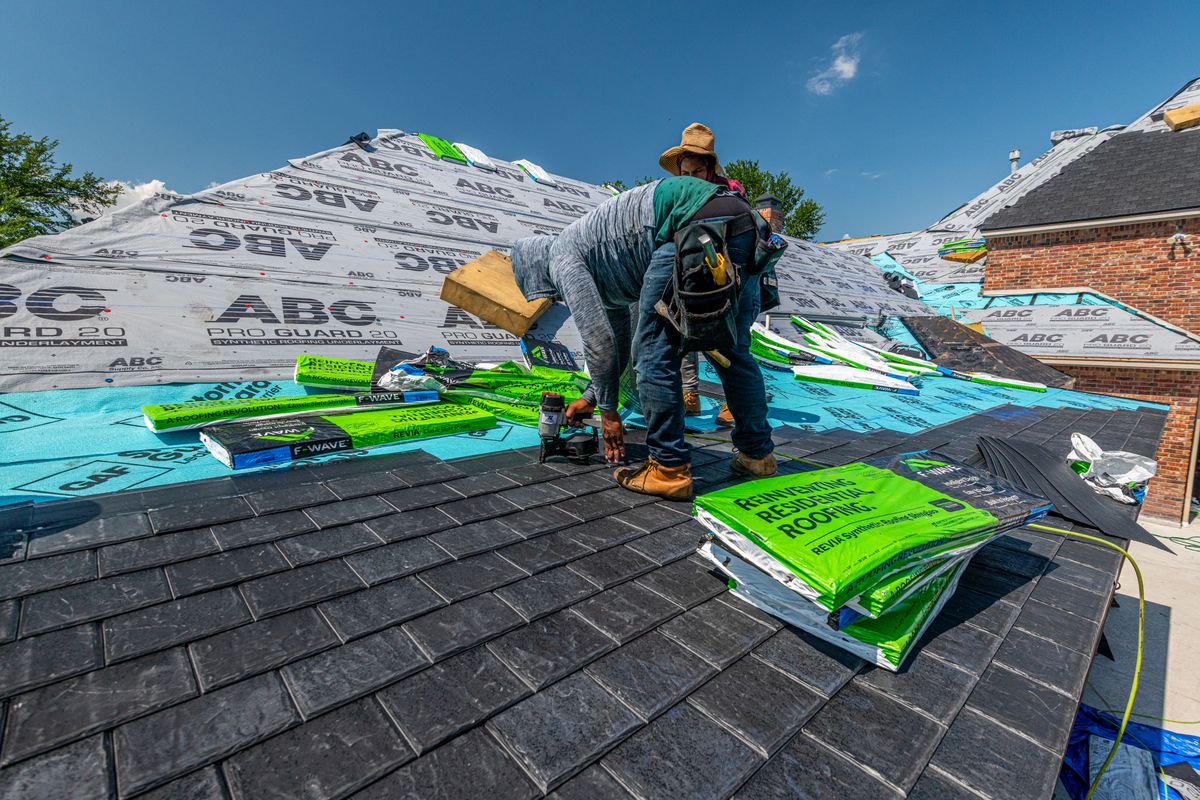
She calls yours first — local, strong reviews, a website full of Southwest Florida claims you got reopened. You're not there. You're on a roof in Naples with a moisture meter, or across a table from a carrier's adjuster in Bonita Springs arguing over a scope sheet. Your phone rings out to voicemail.
She calls the next firm on the list. They answer on the second ring, ask what the carrier paid and what the roofer quoted, and book a free inspection of her house for tomorrow morning. When that claim settles for an additional $30,000, the firm that answered earns its percentage on every dollar of it. Yours never knew she called.
The Stats
Public adjusting runs on phone calls made in a short window of anger and arithmetic. A homeowner tolerates the insurance company right up until the low check arrives — then she has days of motivation to do something about it before life takes over and the check gets spent on a partial fix.
Roughly 6 in 10 inbound calls to small businesses go unanswered (BrightLocal, 2024). About 8 in 10 callers who reach voicemail hang up without leaving a message. CallRail reported in 2025 that 82 percent of callers move on to a competitor after one missed call, and 78 percent have permanently abandoned a business after an unanswered call.
In this business, the first firm through the door usually keeps the claim. Once a homeowner signs with an adjuster and the reinspection is scheduled, she stops calling — a signed claim does not shop around. Whoever answers first doesn't just win a lead. They take the claim off the market entirely.

What One Missed Call Is Worth
An underpaid roof or water claim in Lee or Collier County commonly settles for $20,000 to $60,000 more once someone who works for the homeowner — not the carrier — documents the damage and reopens it. Florida caps public adjuster fees by law: 10 percent during a declared state of emergency for the first year, 20 percent otherwise. At the conservative end, one signed claim is worth about $3,000 on a $30,000 additional recovery at 10 percent — bigger claims pay considerably more.
Take that $3,000 as the conservative average for one signed claim — the low end, at the emergency cap, leaving out the commercial claims, the fire and plumbing losses between storms, and the neighbors who call after they watch your sign go up in her yard.
Now run a conservative month. Say you miss just 5 real inquiries — a few while you're on roofs and in carrier meetings, a few in the evening when homeowners are sitting at the kitchen table with the check in front of them.
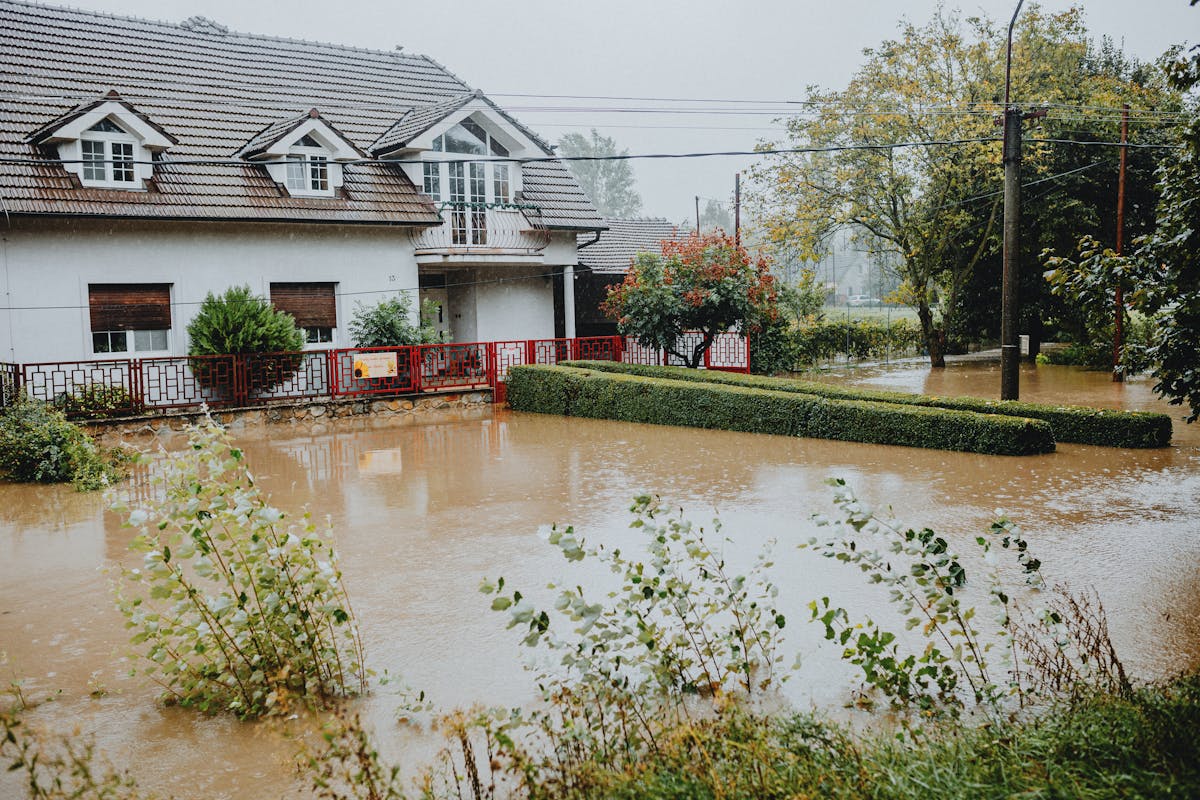
Say only 3 signed. Three lost claims at that low-end $3,000 average is $9,000 a month in fees — and that assumes every claim you lose is a small one at the capped rate. The month one of those missed calls was a gutted house in Fort Myers Beach, the real loss is in another league entirely.
Why It Keeps Happening
You're on roofs and at inspections all day. Documenting damage means ladders, attics, moisture meters, and photo sets in houses with no power and no signal worth having. The licensed adjuster homeowners want to reach is standing somewhere a ringing phone doesn't get answered — and shouldn't, halfway up a ladder.
Your calls spike exactly when you can least answer them. After a storm, every past inquiry, every neighbor, and every low check in three counties produces calls in the same two weeks. That surge is your whole year's pipeline arriving at once, while every adjuster you have is in the field from daylight to dark. The calls you miss in surge season are not a slow month — they are the season.
Homeowners sign with the first adjuster who looks. There is no money out of pocket to hire you — the fee comes out of the recovery — so the homeowner is not really price-shopping. She is trust-shopping, fast, while she's angry at her carrier. The first firm that answers and books the inspection gets the signature. Voicemail gets nothing signed.
You're a field operation, not an office. Inspections, carrier meetings, scope write-ups, and the phone all land on the same few people — and the phone is the only one that can be ignored without a roof leaking on somebody. So it loses, one claim at a time.

The Fix
An AI receptionist answers your phone on the first ring, 24 hours a day, so the homeowner with the low check in her hand reaches a live voice instead of voicemail — even at 7:30 PM, even while your whole firm is on roofs across the county.
She takes the intake your adjusters actually need. Name, property address, and callback number. Who the carrier is and whether a claim is open. What happened and when — storm, roof leak, broken pipe, fire — and whether the carrier has inspected, paid, denied, or gone quiet, because each gets handled differently. Whether a contractor has quoted the real repair, and whether a mortgage company is holding the check.
She books the inspection straight into your calendar. You get a text with the full details the moment the call ends — carrier, damage type, what they've paid — so your adjuster rolls up already knowing the fight. She explains the firm works on a percentage of what it recovers, without promising an outcome, because nobody honest can quote one over the phone.
She also catches the calls that build the firm between storms: the plumbing loss in Lehigh Acres in February, the condo manager with three buildings, the neighbor who wants an inspection before she accepts her own check.
You stay on the roof. She makes sure the next inspection is already booked when you come down.
Run Your Own Numbers
Do the math on your own missed calls.
Put in your average job value and how many calls you miss in a typical week. For an adjusting firm, use your average fee on one signed claim.
Then look at https://voiceanna.com to see how it works.
Then call (386) 334-2561 and ask for Anna. She's an AI receptionist — hear for yourself.
About the author — Scott Riefler is the founder of VoiceAnna, the AI receptionist that helps small businesses stop missing calls. Learn more at voiceanna.com or call (386) 334-2561 and ask for Anna.


Comments
Post a Comment